Showing posts with label Henry Paulson. Show all posts

Thursday, May 2, 2013

Hank Paulson Burned As Another Electric Car Maker Goes Up In Flames

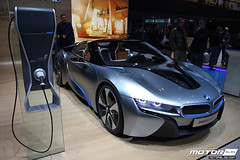
Electric Cars at NAIAS 2013
It would appear that (apart from Tesla, for now) that any thing related to electric cars is going up in flames. From Fisker's fubar (and blowing all that hard-earned government funding) and Chevy's Volt dysphoria to A-123 Systems (the Lithium-Ion battery-maker) and now Coda - which Yahoo Finance notes was among an emerging crop of California startups seeking to build emission-free electric cars three years ago.

After selling just 100 of its $37,250 five-passenger vehicles, Coda filed Chapter 11 today taking a few well-known investors with it. On the bright side, the government was not involved (from what we can tell), but on the even brighter side, none other than former US Treasury Secretary Hank Paulson was among those burned by the company going up in flames (as was Harbinger's Phil Falcone).

Despite the $300 million the company managed to raise, that quickly went and unable to raise an additional $150 million in new funding (we suspect blaming 'market conditions' for its mere $22million raise), Coda had no choice (and Fortress was more than happy to scoop it up and provide the DIP - the cars will make for fancy paperweights in a collateral liquidation). 'Green' is the new 'red' as it seems when it comes to electric cars, regardless of funding source - private or public - it goes up in flames. Read more >>
Enhanced by Zemanta

Monday, January 7, 2013

Secret and Lies of the Bailout

English: Wall Street sign on Wall Street
The federal rescue of Wall Street didn’t fix the economy – it created a permanent bailout state based on a Ponzi-like confidence scheme. And the worst may be yet to come

Matt Taibbi


It has been four long winters since the federal government, in the hulking, shaven-skulled, Alien Nation-esque form of then-Treasury Secretary Hank Paulson, committed $700 billion in taxpayer money to rescue Wall Street from its own chicanery and greed. To listen to the bankers and their allies in Washington tell it, you'd think the bailout was the best thing to hit the American economy since the invention of the assembly line. Not only did it prevent another Great Depression, we've been told, but the money has all been paid back, and the government even made a profit. No harm, no foul – right?

Wrong.

It was all a lie – one of the biggest and most elaborate falsehoods ever sold to the American people. We were told that the taxpayer was stepping in – only temporarily, mind you – to prop up the economy and save the world from financial catastrophe. What we actually ended up doing was the exact opposite: committing American taxpayers to permanent, blind support of an ungovernable, unregulatable, hyperconcentrated new financial system that exacerbates the greed and inequality that caused the crash, and forces Wall Street banks like Goldman Sachs and Citigroup to increase risk rather than reduce it. The result is one of those deals where one wrong decision early on blossoms into a lush nightmare of unintended consequences. We thought we were just letting a friend crash at the house for a few days; we ended up with a family of hillbillies who moved in forever, sleeping nine to a bed and building a meth lab on the front lawn.

But the most appalling part is the lying. The public has been lied to so shamelessly and so often in the course of the past four years that the failure to tell the truth to the general populace has become a kind of baked-in, official feature of the financial rescue. Money wasn't the only thing the government gave Wall Street – it also conferred the right to hide the truth from the rest of us. And it was all done in the name of helping regular people and creating jobs. "It is," says former bailout Inspector General Neil Barofsky, "the ultimate bait-and-switch."

The bailout deceptions came early, late and in between. There were lies told in the first moments of their inception, and others still being told four years later. The lies, in fact, were the most important mechanisms of the bailout. The only reason investors haven't run screaming from an obviously corrupt financial marketplace is because the government has gone to such extraordinary lengths to sell the narrative that the problems of 2008 have been fixed. Investors may not actually believe the lie, but they are impressed by how totally committed the government has been, from the very beginning, to selling it. Read more >>

Enhanced by Zemanta

Wednesday, November 24, 2010

U.S. Military War Gaming for Large Scale Economic Breakdown and Civil Unrest


Mac_Slavo
The majority of Americans believe that recent government intervention into financial markets, the economy and corporate insolvency has reversed the economic downturn which was described by former Treasury Secretary Hank Paulson as being “on the brink” in 2008. The stimulus, bailouts and unrelenting quantitative easing by the Federal Reserve have thus far been perceived as having averted the further erosion of the U.S. real estate and equities markets. And though the Federal Reserve and economic analysts have recently readjusted their economic growth forecasts downward for the next six months, Americans no longer have to worry about, as Rep. Brad Sherman (D-CA) said on the house floor in October of 2008, the sky falling, multi-thousand point drops in stock markets and martial law in America.

The recovery - if our government, the Federal Reserve and mainstream media are to be believed - is on the road to recovery - albeit slowly and with some more pain ahead.

If we’ve “prevented economic collapse” and “avoided the depression many feared,” according to President Obama, inquiring minds are asking why the Pentagon and US Military are actively and aggressively engaged in planning responsive action to large scale economic breakdown and civil unrest scenarios:

Ever since the crash of 2008 the defense intelligence establishment has really been paying a lot of attention to global markets and how they can serve as a threat to U.S. national security interests. At one upcoming seminar next month they’re taking a look at a lot of the issues.

According to the report, the Army has spent time on financial market trading floors with JP Morgan and others, in the hopes that they can learn more about how a financial and economic attack may occur, and what the ramifications of such attacks on US stocks and bonds may be.

The Army, in a year-long war games series called Unified Quest 2011, is looking at a variety of possibilities and how to deal with them, including:

* the implications of “large scale economic breakdown” inside of the United States
* how to maintain “domestic order amid civil unrest”
* and ways to deal with fragmented global power and drastically lower budgets

Clearly, the U.S. government is making contingency plans to deal with a worst-case, all-out-collapse scenario of not only the economy, but our social and political systems. More...


Enhanced by Zemanta

Wednesday, March 10, 2010

Goldman Sucks


Goldman Sucks explores the massive corruption of Goldman's Sachs.

Wednesday, December 2, 2009

Goldman Sachs bankers stockpiling weapons in case people revolt

Image representing Goldman Sachs as depicted i...Image via CrunchBase

Alice Schroeder
Bloomberg
“I just wrote my first reference for a gun permit,” said a friend, who told me of swearing to the good character of a Goldman Sachs Group Inc. banker who applied to the local police for a permit to buy a pistol. The banker had told this friend of mine that senior Goldman people have loaded up on firearms and are now equipped to defend themselves if there is a populist uprising against the bank.

I called Goldman Sachs spokesman Lucas van Praag to ask whether it’s true that Goldman partners feel they need handguns to protect themselves from the angry proletariat. He didn’t call me back. The New York Police Department has told me that “as a preliminary matter” it believes some of the bankers I inquired about do have pistol permits. The NYPD also said it will be a while before it can name names.

While we wait, Goldman has wrapped itself in the flag of Warren Buffett, with whom it will jointly donate $500 million, part of an effort to burnish its image -- and gain new Goldman clients. Goldman Sachs Chief Executive Officer Lloyd Blankfein also reversed himself after having previously called Goldman’s greed “God’s work” and apologized earlier this month for having participated in things that were “clearly wrong.”

Has it really come to this? Imagine what emotions must be billowing through the halls of Goldman Sachs to provoke the firm into an apology. Talk that Goldman bankers might have armed themselves in self-defense would sound ludicrous, were it not so apt a metaphor for the way that the most successful people on Wall Street have become a target for public rage.

Pistol Ready

Common sense tells you a handgun is probably not even all that useful. Suppose an intruder sneaks past the doorman or jumps the security fence at night. By the time you pull the pistol out of your wife’s jewelry safe, find the ammunition, and load your weapon, Fifi the Pomeranian has already been taken hostage and the gun won’t do you any good. As for carrying a loaded pistol when you venture outside, dream on. Concealed gun permits are almost impossible for ordinary citizens to obtain in New York or nearby states.

In other words, a little humility and contrition are probably the better route.

Until a couple of weeks ago, that was obvious to everyone but Goldman, a firm famous for both prescience and arrogance. In a display of both, Blankfein began to raise his personal- security threat level early in the financial crisis. He keeps a summer home near the Hamptons, where unrestricted public access would put him at risk if the angry mobs rose up and marched to the East End of Long Island.

To the Barricades

He tried to buy a house elsewhere without attracting attention as the financial crisis unfolded in 2007, a move that was foiled by the New York Post. Then, Blankfein got permission from the local authorities to install a security gate at his house two months before Bear Stearns Cos. collapsed.

This is the kind of foresight that Goldman Sachs is justly famous for. Blankfein somehow anticipated the persecution complex his fellow bankers would soon suffer. Surely, though, this man who can afford to surround himself with a private army of security guards isn’t sleeping with the key to a gun safe under his pillow. The thought is just too bizarre to be true.

So maybe other senior people at Goldman Sachs have gone out and bought guns, and they know something. But what?

Henry Paulson, U.S. Treasury secretary during the bailout and a former Goldman Sachs CEO, let it slip during testimony to Congress last summer when he explained why it was so critical to bail out Goldman Sachs, and -- oh yes -- the other banks. People “were unhappy with the big discrepancies in wealth, but they at least believed in the system and in some form of market-driven capitalism. But if we had a complete meltdown, it could lead to people questioning the basis of the system.”

Torn Curtain

There you have it. The bailout was meant to keep the curtain drawn on the way the rich make money, not from the free market, but from the lack of one. Goldman Sachs blew its cover when the firm’s revenue from trading reached a record $27 billion in the first nine months of this year, and a public that was writhing in financial agony caught on that the profits earned on taxpayer capital were going to pay employee bonuses.

This slip-up let the other bailed-out banks happily hand off public blame to Goldman, which is unpopular among its peers because it always seems to win at everyone’s expense.

Plenty of Wall Streeters worry about the big discrepancies in wealth, and think the rise of a financial industry-led plutocracy is unjust. That doesn’t mean any of them plan to move into a double-wide mobile home as a show of solidarity with the little people, though.

Cool Hand Lloyd

No, talk of Goldman and guns plays right into the way Wall- Streeters like to think of themselves. Even those who were bailed out believe they are tough, macho Clint Eastwoods of the financial frontier, protecting the fistful of dollars in one hand with the Glock in the other. The last thing they want is to be so reasonably paid that the peasants have no interest in lynching them.

And if the proles really do appear brandishing pitchforks at the doors of Park Avenue and the gates of Round Hill Road, you can be sure that the Goldman guys and their families will be holed up in their safe rooms with their firearms. If nothing else, that pistol permit might go part way toward explaining why they won’t be standing outside with the rest of the crowd, broke and humiliated, saying, “Damn, I was on the wrong side of a trade with Goldman again.”